The House Has Potential — But the Price Tag on Repairs Is Stopping You
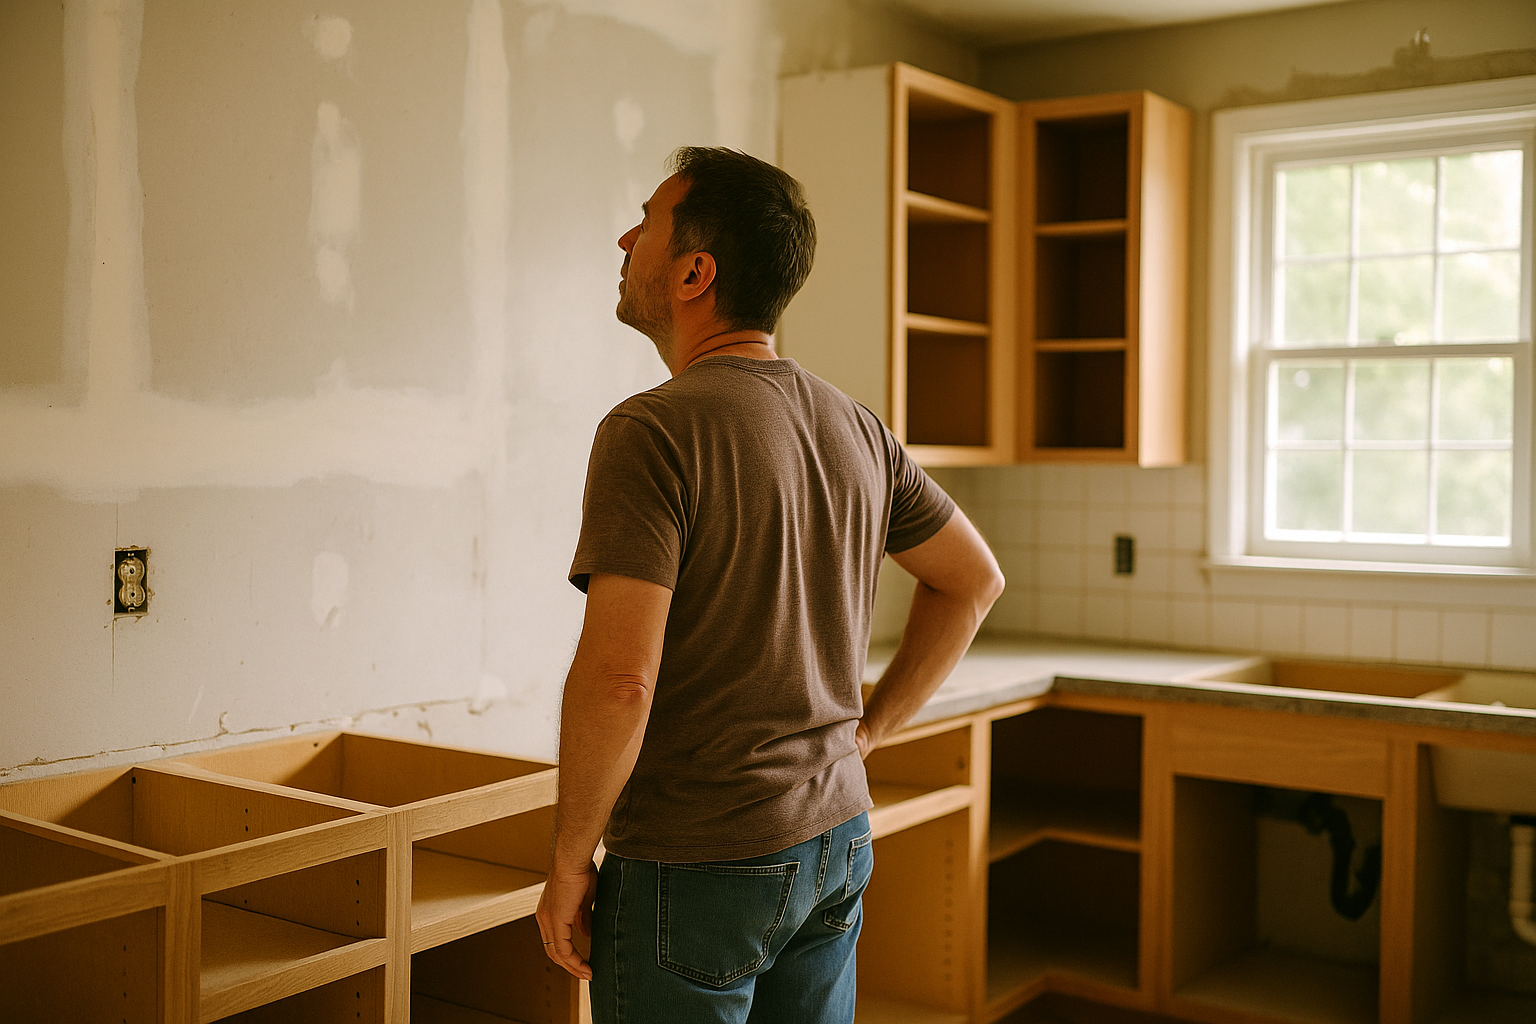
You found a house in a neighborhood you love. The location is right, the lot is right, and the price reflects the fact that the kitchen is dated, the bathrooms need work, and there may be some deferred maintenance hiding behind the walls. The problem is that after the down payment, you do not have a pile of cash left over to fund a full renovation.
This is one of the most common situations homebuyers and current homeowners face right now. With fewer move-in-ready listings available and home prices remaining elevated across South Florida, many people are taking a serious look at properties they might have passed on before. The question is how to finance not just the purchase, but the work that makes the house actually livable.
That is exactly where renovation loans come in — and it is an area where Stairway Mortgage’s renovation loan programs can open doors that a standard mortgage simply cannot.
What a Renovation Loan Actually Does
A renovation loan bundles the cost of buying or refinancing a home together with a budget for repairs and improvements — all into one loan, with one closing. Instead of scrambling to line up a personal loan, drain your savings, or max out a credit card after you move in, the renovation funds are built into the mortgage from the start.
The contractor gets paid as work is completed through a draw process, which protects both you and the lender. You are not handing over a lump sum before a single nail is driven.
These loans are not niche or experimental. They have been around for decades under programs backed by the federal government, and they are a legitimate path that many buyers and homeowners use every year to take on properties that need work.
Who This Type of Loan Could Work For
Renovation financing is not just for people buying distressed properties at auction. It could be a practical fit in a range of situations:
Buyers shopping in competitive markets. Homes that need work often sit longer and attract fewer competing offers. A renovation loan may let you buy that property and fund the updates without paying a premium for a fully finished home.
Current homeowners who want to stay put. Moving costs money. Between real estate commissions, closing costs, and the emotional weight of relocating, many homeowners are choosing to invest in their current home rather than chase a new one. A renovation refinance could allow you to access equity and fund meaningful upgrades.
People inheriting or receiving a gifted property. Sometimes a home comes to you in a condition that needs attention before it is ready to live in or rent. A renovation loan may help you get it there without coming out of pocket for every dollar.
Landlords and small investors. If you own a rental property that has fallen behind on updates, certain renovation loan programs may apply — though eligibility depends on the specific program and your situation.
The Programs Worth Knowing About
There are a few renovation loan structures that come up most often. The two you are most likely to encounter are the FHA 203(k) and the Fannie Mae HomeStyle Renovation loan.
The FHA 203(k) comes in two versions. The limited version is designed for smaller projects — cosmetic updates and repairs that fall under a set dollar cap. The standard version handles more extensive work, including structural changes, room additions, and major system replacements. FHA loans allow a down payment as low as three and a half percent for qualified borrowers, which can make this option accessible for buyers who do not have a large cash reserve.
The Fannie Mae HomeStyle loan is a conventional option that tends to offer more flexibility on property types and the kinds of improvements you can fund — including luxury upgrades that FHA programs may not cover. It can also be used on investment properties under certain conditions.
Each program has its own requirements for contractor qualifications, timelines, and draw schedules. Understanding which one fits your project is part of what Jim Blackburn, NMLS #1072866, does when he works through the numbers with you.
You can also use our mortgage calculators to get a rough sense of how renovation costs folded into a loan might affect your monthly picture before you ever sit down with a lender.
What to Expect From the Process
Renovation loans take more coordination than a standard purchase loan, and being realistic about that upfront saves frustration later.
Before closing, you will need a detailed contractor bid — sometimes called a work write-up — that spells out exactly what will be done and at what cost. The lender will use this to determine the after-renovation value of the property, which is what the loan is ultimately based on. That appraisal looks at what the home will be worth once the work is finished, not what it is worth in its current condition.
After closing, the renovation funds sit in an escrow account. As the contractor completes phases of the work, inspections are ordered and draws are released. You typically begin making your full mortgage payment — including the renovation portion — right away, even while the work is still in progress.
This structure means communication between you, your contractor, and your loan team is important throughout. Choosing a contractor who has experience with renovation loan draw processes makes a meaningful difference in how smoothly things go.
For a broader look at how a mortgage transaction moves from application to closing, our step-by-step process is a good place to start.
Working With Stairway Mortgage in Fort Lauderdale
Stairway Mortgage is based in Fort Lauderdale and serves homeowners and buyers throughout Florida. Renovation lending is one of the more complex areas of mortgage finance, and it rewards working with someone who has done it before and knows where things can go sideways.
When you connect with the team, you are working with people who will ask the right questions about your project scope, your timeline, and your financial situation before pointing you toward a specific program. The goal is to match you with a loan structure that actually fits — not to push you toward something that creates problems six months in.
If you are trying to understand your full range of options before committing to anything, reviewing the available loan programs is a practical first step.
You can also reach the team directly at (954) 993-1625.
Take the Next Step When You Are Ready
Renovation loans are one of the more underused tools in residential lending. Many buyers and homeowners do not realize they exist or assume they are too complicated to pursue. In practice, they could be the path that turns a property with potential into the home you actually want — or the upgrade that keeps you in a neighborhood you already love.
When you are ready to explore what might work for your situation, Talk to Our Team and let Jim Blackburn, NMLS #1072866, help you think through the options.
Or if you prefer to start by looking at what programs might fit, go ahead and See My Options — no commitment required.