
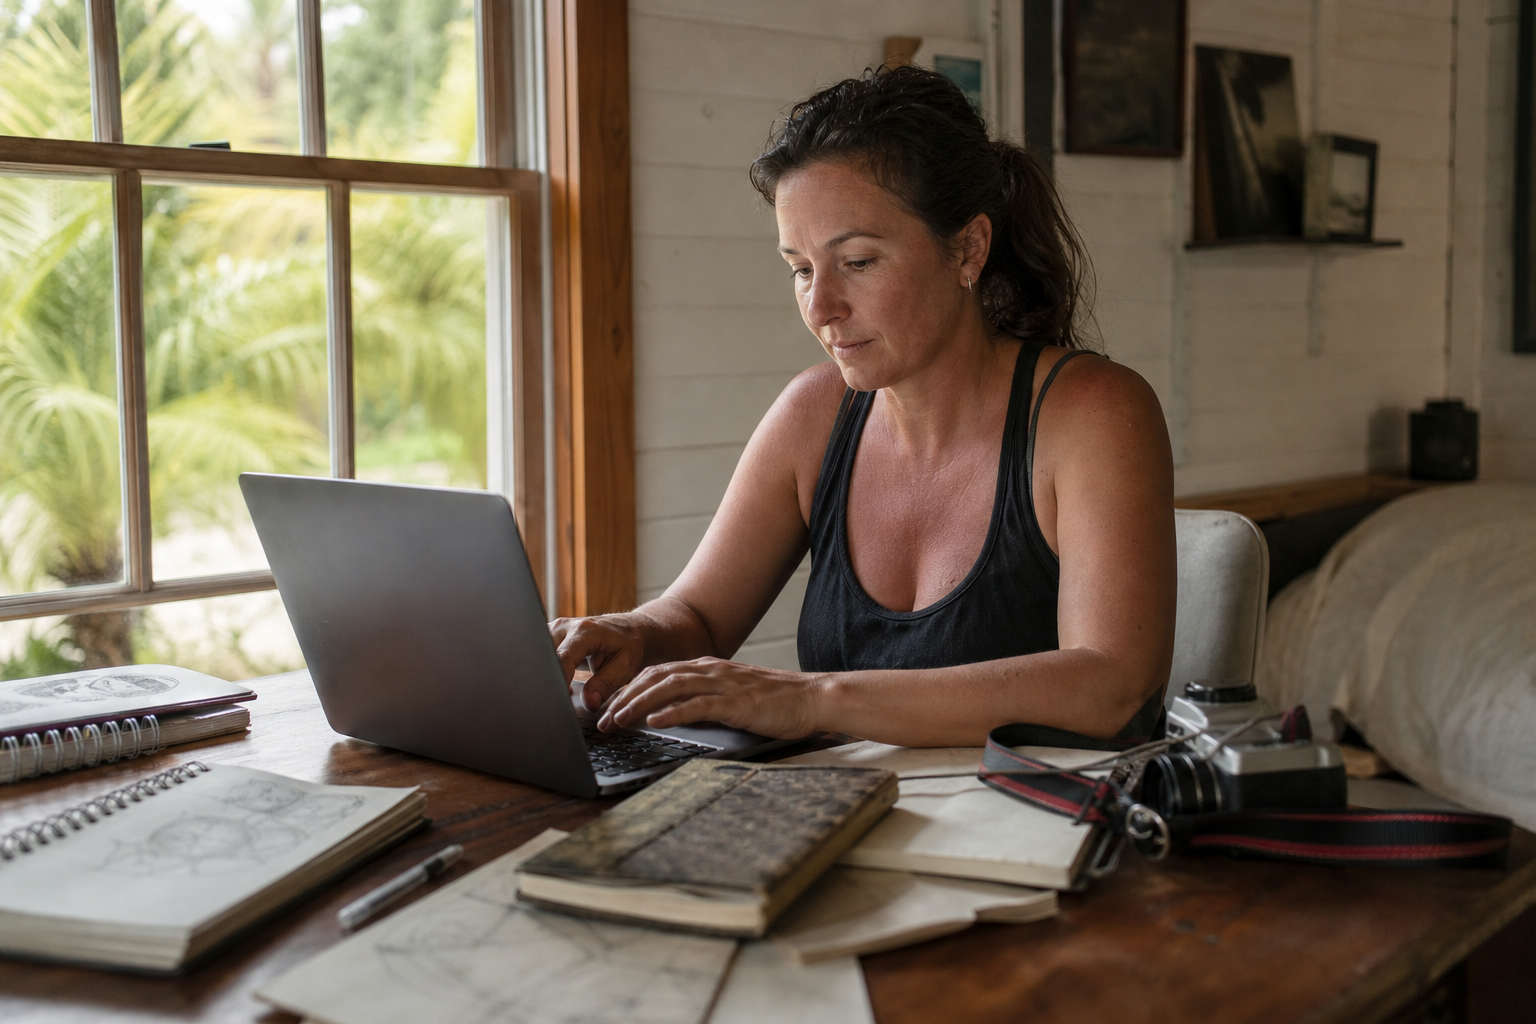
When Your Income Doesn’t Fit a Pay Stub
You finished a brand project last month, invoiced three clients this week, and have another contract lined up — but when you sit down to think about buying a home in Baker County, that momentum can feel invisible on paper. Mortgage applications were built around W-2 employees with predictable paychecks. If you’re a freelance designer, photographer, copywriter, musician, or any other kind of 1099 creative, your income is real — it just looks different.
That difference matters in Baker County specifically. The area around Macclenny and the broader rural stretches of the county attract buyers looking for land, space, and a slower pace than South Florida offers. Properties here often include acreage, and many neighborhoods fall within USDA-eligible rural zones. That’s a genuine opportunity — if you can get your income documentation in order before you apply.
This guide is written for you: the freelancer, the independent contractor, the creative professional building something on your own terms.
Why Traditional Income Verification Doesn’t Work for You
Most mortgage underwriters are trained to look at W-2 forms and employer verification letters. When your income comes from a dozen different clients across the year, that process gets more complicated — not impossible, just different.
Lenders evaluating self-employed borrowers typically look at:
- Two years of federal tax returns (personal and, if applicable, business)
- A current profit-and-loss statement
- Bank statements showing consistent deposits
- 1099 forms from clients
The challenge many freelancers face is that their tax returns show lower net income than they actually deposited, because business deductions — software subscriptions, equipment, home office — reduce taxable income. That’s smart tax strategy, but it can shrink the income figure a lender uses to calculate what you may afford.
Understanding this tension early gives you time to plan. If you’re thinking about buying in Baker County in the next one to two years, the decisions you make on your taxes today will shape what a lender sees tomorrow.
Income Documentation Strategies Worth Knowing
There’s no single path through underwriting for 1099 earners. The approach that works for a freelance videographer with a single LLC may look nothing like what works for a graphic designer juggling five recurring clients. That’s why working with someone who understands how loan programs are structured for non-traditional earners matters more than it might for a salaried borrower.
A few documentation approaches that often come up for freelancers:
Bank statement loans. Some loan programs allow lenders to average 12 to 24 months of bank deposits rather than relying on tax returns alone. This can reflect a truer picture of your cash flow — especially if your net income on paper is reduced by legitimate business deductions.
Conventional loans with two-year self-employment history. If you’ve been freelancing for at least two full tax years and your income is stable or growing, conventional loan programs may be an option. The income figure used is typically an average of your net self-employment income across both years.
USDA loans. Because much of Baker County qualifies as a rural area under USDA guidelines, freelancers who meet income and credit requirements could potentially access USDA loan programs, which in many cases allow for no down payment. Exploring this through our loan programs overview is a useful starting point.
None of these paths come with a promise of approval — every file is different. But knowing your options before you start shopping for a home puts you in a far stronger position.
What Baker County’s Market Means for Freelance Buyers
Baker County sits in northeast Florida, roughly an hour west of Jacksonville. Macclenny is the county seat, and the surrounding area has the character of a rural agricultural community — not a dense suburban market. That has real implications for homebuyers.
Properties in Baker County often include land, manufactured housing, or older construction that may not meet the condition requirements of some loan programs. It’s worth understanding which programs are available for the specific property type you’re interested in, especially if you’re drawn to a fixer-upper or a rural parcel.
The rural character of Baker County also means USDA loan eligibility is a realistic conversation — not a long shot. For a freelancer who has managed their income documentation well, that could open access to financing that doesn’t require a large down payment up front.
If you’re exploring what you might afford or how different loan structures affect your monthly picture, the mortgage calculators on our site can give you a working estimate to start from.
Getting Organized Before You Apply
The single most consistent piece of guidance for freelancers approaching a mortgage: start the documentation process earlier than you think you need to.
Here’s a practical checklist to work through:
- Locate your last two years of federal tax returns (personal and business if applicable)
- Ask your accountant to prepare a current profit-and-loss statement
- Gather 12 to 24 months of business and personal bank statements
- Pull together your 1099 forms from clients
- Check your credit report for any issues worth addressing before you apply
- Think through your down payment sources and make sure funds have been in your account long enough to be documented
None of this needs to be perfect on day one. But having it organized means that when you sit down with a loan originator, the conversation can focus on strategy rather than scavenger hunts.
You can also review our step-by-step process to understand how the mortgage journey typically unfolds from application through closing.
Working with Jim Blackburn in Baker County
Jim Blackburn, NMLS #1072866, leads Stairway Mortgage with a focus on borrowers whose financial lives don’t fit a standard mold. That includes freelancers, independent contractors, creatives, and anyone whose income tells a story that takes a little more explaining.
If you’re a 1099 earner looking to buy in Baker County — whether that’s a home in Macclenny, a rural property with acreage, or anything in between — the approach starts with understanding your income picture clearly and matching it to programs that may work for your situation.
Stairway Mortgage works with borrowers across Florida, and the team can be reached directly at (954) 993-1625. There’s no pressure, no jargon, and no expectation that your situation looks like everyone else’s.
For freelancers who want to understand what’s possible before they commit to anything, the creative earners page offers a useful overview of how Stairway Mortgage approaches non-traditional income.
Your Next Step
Buying a home as a freelancer in Baker County isn’t a longer shot than it is for a salaried employee — it’s a different process that rewards preparation and the right guidance. Jim Blackburn, NMLS #1072866, and the Stairway Mortgage team are ready to walk through your specific income situation without judgment or assumptions.
When you’re ready to explore what may be available to you, Talk to Our Team or See My Options to get started.